The short version. A bank statement loan replaces tax returns with 12 or 24 months of deposits. The lender totals your qualifying deposits, applies an expense factor, and treats what is left as your income. Available on Virginia primary homes, second homes and rentals. Call or text me at 704-890-7168 and I will run the number before anyone pulls your credit.
A bank statement loan is a non-QM mortgage. That label sounds alarming and it is not: it simply means the loan sits outside the Qualified Mortgage safe harbour the Consumer Financial Protection Bureau defined after 2008. The lender still has to make a reasonable, good-faith determination that you can repay, which is a federal requirement under the ability-to-repay rule. Nothing about this product skips that.
What changes is the evidence. Instead of reading a Schedule C or a K-1 and accepting the taxable income at the bottom, the underwriter reads your bank statements and builds an income figure from deposits. For a business owner who writes off aggressively and legally, those two numbers can be a universe apart.
It is not a stated income loan, which is the assumption I spend the most time correcting, because nobody is taking your word for anything here and you will almost certainly hand over more paperwork than the W-2 buyer competing against you for the same house, not less. The documents are simply different ones.
Four steps, and the third one decides almost everything.
Step three is where two lenders look at identical statements and reach wildly different conclusions. Expense factors commonly run somewhere between about 20 percent and 50 percent depending on the lender, the account type and the kind of business you operate. On $600,000 of annual business deposits, a 50 percent factor produces $300,000 of qualifying income and a 20 percent factor produces $480,000. Same statements. Same borrower. A difference large enough to decide whether you get the house.
Three things tend to move that factor in your favour:
This is the part almost nobody explains before you apply, and it is the most common reason a borrower’s own arithmetic does not match the underwriter’s.
| Deposit | Usually counts? | Why |
|---|---|---|
| Customer payments, card settlements, invoice payments | Yes | Ordinary revenue, which is exactly what the method is built to measure |
| Transfers between your own accounts | No | Counting both sides would inflate the same dollar twice |
| Loan proceeds, lines of credit, credit card advances | No | Borrowed money is not income |
| A large one-off that does not match your pattern | Often questioned | Expect to document the source, and expect it to be excluded if you cannot |
| Cash deposits | Varies, often limited | Hard to trace to the business, so many lenders cap how much counts |
| Gifts, tax refunds, insurance settlements, asset sales | No | Not recurring revenue |
| Rental income already used elsewhere in the file | No | Double counting again |
Two practical consequences follow. Keep business revenue flowing into a business account and personal money out of it, because an account where a client payment, a tax refund, a transfer from savings and your spouse’s paycheck all land in the same week gives an underwriter a reason to exclude far more than you expected. And if you moved a large sum around during the review window, say so at the outset rather than letting someone find it in week three and start asking questions with a closing date already on the calendar.
Most borrowers assume twelve months is the easier road. Sometimes it is. Often it is not.
Twenty-four months smooths out a bad quarter. If your business had a soft stretch twelve months ago and a strong one since, the shorter window flatters you; if the soft stretch was recent, the longer window is your friend because the stronger earlier period gets to pull the average back up. Lenders also tend to price the twelve-month option slightly less favourably because it gives them less history to look at. Run both. The spread between them is frequently bigger than people expect, and choosing wrong costs real qualifying income.
Rarely the thing the borrower was worried about. In practice it tends to be one of these:
That last one is worth sitting with. The product is unusually lender-dependent, so the cost of guessing is higher here than on a conventional loan.
Numbers make this concrete in a way that explanation does not. The following is an illustration, not a client, and every figure is hypothetical.
Say you run a marketing consultancy in Richmond. Revenue lands in a business checking account and averages $50,000 a month, so $600,000 across the year. You pay yourself $8,000 a month and leave the rest in the company. Your tax return, after a home office, a vehicle, software, subcontractors and a retirement contribution, shows taxable income of $104,000.
A conventional lender qualifies you on roughly that $104,000, which at current payment levels is not buying the $900,000 house you are looking at in the West End.
Now run the same year three ways.
| Approach | Input | Deduction applied | Annual qualifying income |
|---|---|---|---|
| Conventional, tax returns | Schedule C net plus add-backs | All deductions already taken | About $104,000 |
| Business statements, lender default | $600,000 deposits | 50 percent expense factor | $300,000 |
| Business statements, CPA letter at 25 percent | $600,000 deposits | 25 percent expense factor | $450,000 |
| Personal statements | $96,000 paid to yourself | Little or none | About $96,000 |
Look at the bottom row. Personal statements are usually the friendlier option, and here they are the worst one available, because you leave most of the profit inside the business and the method can only count what actually reached you. That single decision swings the file by more than $350,000 of qualifying income.
Now suppose the same consultancy spends heavily on subcontractors and the true expense ratio is 45 percent. The CPA letter stops helping, the lender’s 50 percent default is close to honest, and the right answer may well be a profit and loss program instead. The method is not a trick. It is a question of which measurement describes your business most accurately, and that genuinely differs from one borrower to the next.
Bank statement files are not slower than conventional ones by nature. They go sideways when documents arrive late, so the order matters.
Three state-level details change the shape of these files.
The conforming limit splits the state. For 2026 the baseline one-unit limit is $832,750 and the high-cost ceiling is $1,249,125. The Washington metro counties in Northern Virginia carry the ceiling; Richmond, Virginia Beach, Charlottesville, Roanoke and most of the rest carry the baseline. It matters here because bank statement programs layer their own tiers on top of loan size, and crossing into jumbo territory usually means a larger down payment and heavier reserves. A $1.1M purchase in Arlington and the identical purchase in Richmond are not the same transaction. There is more detail on that split on the Virginia mortgage broker page.
Northern Virginia borrowers are often on the wrong product. The region runs on government contracting, and a 1099 consultant with no business overhead frequently does better on a 1099 program than a bank statement one, because the 1099 totals skip the expense-factor haircut entirely. If you are paid on 1099s rather than running a company with real costs, ask about both before assuming bank statements are your answer. The Northern Virginia page goes deeper on contract-cycle income.
Condos need checking early. Non-QM lenders apply their own project review to condominiums, and a building that sails through a conventional loan can still fail a specific lender’s overlay. In Arlington, Alexandria and the Virginia Beach oceanfront, where condo stock is a meaningful share of the market, the project should be reviewed before you are emotionally committed to the unit.
Licensing, for what it is worth: mortgage brokers operating in Virginia are regulated by the Virginia State Corporation Commission through its Bureau of Financial Institutions, and every originator carries an NMLS ID you can verify yourself on NMLS Consumer Access. Mine is 926762.
Search this topic and you will find lists of lender names. Try applying to them and you will mostly hit a wall, because the overwhelming majority of bank statement programs sit with wholesale lenders who do not take consumer applications at all, have no retail branch, no consumer call centre and no intention of building either, since their entire distribution model runs through brokers. That is not a gatekeeping trick. It is just how the segment is built.
So the honest answer to “who offers bank statement loans” is that you reach them through someone like me, and the useful question is not which lender has the best advertised rate but which lender’s expense factor and deposit rules fit your particular business. I have written that up in more detail on who actually offers bank statement loans.
No credit pull, no application, no obligation. Send me:
From that I can tell you what you would qualify on, which lenders fit, and whether a conventional loan would actually serve you better. Sometimes it does, and when it does I will say so.
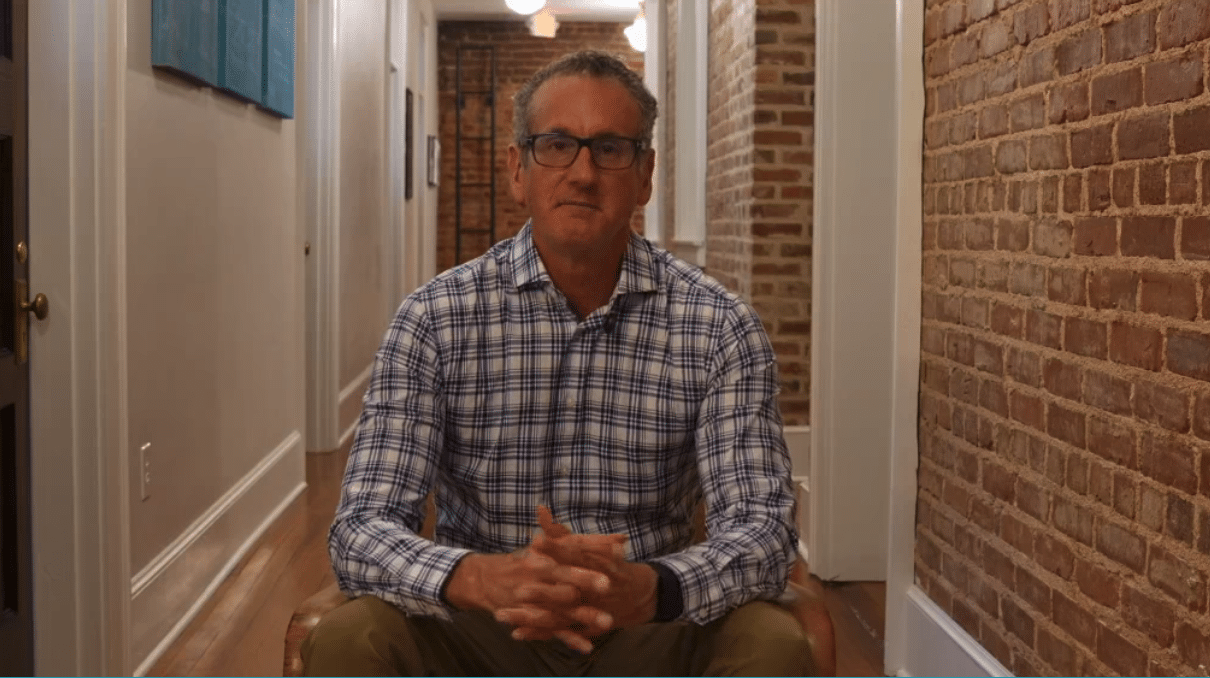
I am Scott Hastings, a mortgage broker with Arbor Financial Group. Self-employed borrowers and real estate investors are effectively my whole book, which means bank statement files are routine here rather than an exception someone has to figure out.
Licensed in 13 states including Virginia. Individual NMLS ID 926762, verifiable on NMLS Consumer Access.
Mortgages by Scott has been accredited by the Better Business Bureau since 2015, and I have been originating mortgages for more than twenty years. WalletHub named me one of the best mortgage brokers in Charlotte for 2026.
Send me the numbers and I will tell you what they support.
Either 12 or 24 months, depending on the program. Twenty-four months is the more common starting point and it can work in your favour if your most recent year was softer than the one before it, since the stronger period pulls the average up. Twelve-month options exist and are sometimes priced slightly less favourably because the lender has less history to review. It is worth calculating both before choosing, because the difference in qualifying income is often larger than borrowers expect.
Usually yes, and it is frequently the better choice. Deposits that have already reached your personal account are generally treated as having cleared your business expenses, so lenders often apply a much smaller expense factor or none at all. The trade-off is that only the money you actually moved to yourself counts, so if you leave significant profit inside the company, business statements may still produce a higher qualifying income despite the haircut.
It is the percentage of your business deposits that a lender assumes went out as business expenses, deducted before your qualifying income is calculated. Factors commonly range from roughly 20 percent to 50 percent depending on the lender, the account type and your industry, because a low-overhead consultancy genuinely does not carry the costs a construction firm does. Many lenders will accept a signed expense statement from your CPA in place of their default assumption, which is often the single most valuable document you can supply.
Most programs start somewhere in the low to mid 600s, with better terms as the score rises. The exact floor depends on the lender, your down payment and the property type, and credit score is only one input among several. Down payment, cash reserves remaining after closing and the consistency of your deposits all move the decision. If your score is borderline, have the conversation before applying anywhere, because each full application costs you a hard inquiry.
Yes, though it is worth comparing against a DSCR loan first. Bank statement programs are available on primary residences, second homes and investment properties. For a rental, a DSCR loan qualifies on the property’s own rent measured against its payment and sets your personal income aside entirely, which is frequently simpler and sometimes cheaper. Which one wins depends on how strong the rent is relative to the payment, so the sensible move is to price both.
Not automatically, but they carry more weight than most borrowers realise. A pattern of overdrafts or returned items reads as cash-flow instability regardless of how healthy the deposit totals look, and it is one of the more common reasons an otherwise strong file gets declined. An isolated incident with a clear explanation is usually manageable. If you know there are several in your recent history, raise it at the start so the file can be placed with a lender whose guidelines can accommodate it.
Send me twelve months of totals and I will run the calculation both ways, personal and business, before anyone pulls your credit.
Text Scott: 704-890-7168 Call 704-890-7168Scott Hastings, individual NMLS #926762. Arbor Financial Group, 121 N Main St Ste 202, Mooresville, NC 28115. Phone and text 704-890-7168. Licensed to originate mortgage loans in Virginia.
Equal Housing Opportunity. This page is general information about loan programs and is not a commitment to lend, a loan approval, or an offer of credit. Program availability, qualifying guidelines, expense factors, credit score minimums, down payment and reserve requirements vary by lender and are subject to change. Nothing here is legal, tax or financial advice. Talk to your own CPA about how your business expenses affect qualifying income.
Loan limit figures are published by the Federal Housing Finance Agency and are current for 2026. Limits are set annually and by county.