The short version. An asset based mortgage converts your eligible assets into a qualifying monthly income using a formula, without requiring you to liquidate or draw on anything. Built for borrowers with substantial savings and little reportable income. Call or text me at 704-890-7168.
The mechanics are simpler than the name suggests. The lender adds up your eligible assets, applies a reduction to the ones that are not cash, then divides the result by a fixed number of months. That quotient is your qualifying income, and it is treated for underwriting purposes as though it arrived every month like a salary.
Nothing is liquidated. You are not required to spend the money, draw on it, or restructure anything. The calculation is a measurement, not an instruction.
The divisor is where lenders diverge hardest. Some use 60 months, some 84, some 120, and a handful tie it to the loan term. That single choice moves your qualifying income by a factor of two between an aggressive lender and a conservative one, on identical assets, which makes it the first question worth asking and the one borrowers almost never think to ask.
Not every dollar carries the same weight.
| Asset | Typically counted at | Notes |
|---|---|---|
| Checking and savings | Full value | Cleanest asset in the file |
| Brokerage, stocks, bonds, mutual funds | A reduced percentage | Discounted for market volatility |
| Retirement accounts, if you are past the penalty-free age | A reduced percentage | Treated similarly to brokerage |
| Retirement accounts, if you are not | A steeper reduction, or excluded | Varies widely by lender, worth shopping |
| Funds already committed to the down payment and closing | Excluded | Cannot serve two purposes at once |
| Business accounts | Case by case | Usually needs evidence you can access them without harming the business |
| Crypto | Often excluded, sometimes if converted and seasoned | Treatment is inconsistent, ask first |
| Property equity, vehicles, collectibles | Not counted | Not liquid in the way this calculation requires |
Two rules catch people out. Assets usually need seasoning, meaning they have to have been sitting in the account for a documented period rather than arriving last week. And the down payment comes out before the calculation runs, so the same dollars cannot both buy the house and qualify you for it.
Four situations, and they look nothing alike on paper.
What unites them is that a conventional lender would look at the tax return, see a small number, and decline a borrower who could write a cheque for the house. That is the gap this product closes.
Illustrative, not a client, and every figure is hypothetical.
A borrower near Charlottesville sold their company two years ago. They hold $2,400,000 across a brokerage account and cash, plus $800,000 in retirement accounts, and they are 58. They are buying at $1,100,000 with $300,000 down. Their tax return shows interest and dividends of about $46,000.
The down payment comes out first, leaving $2,100,000 in the brokerage and cash, plus the retirement accounts.
| Lender approach | Assets counted | Divisor | Monthly qualifying income |
|---|---|---|---|
| Conservative | $1,680,000, retirement excluded at 58 | 120 months | $14,000 |
| Middle | $2,120,000, retirement at a steep reduction | 84 months | About $25,200 |
| Aggressive | $2,320,000, retirement treated more generously | 60 months | About $38,600 |
Same borrower. Same statements. Same week. Monthly qualifying income ranging from $14,000 to $38,600 depending entirely on which lender opens the file, and all three of those approaches are ordinary rather than exotic.
Note also that every one of them beats the $46,000 a year the tax return reports, which is the point. But the spread between them is wider than most borrowers imagine, and it is invisible if you only ever apply to one place.
| Situation | Usually better |
|---|---|
| Large assets, little reportable income, buying a home to live in | Asset based |
| Operating business with steady deposits | Bank statement loan |
| Paid on 1099s with low overhead | 1099 program |
| Buying a rental, and the rent covers the payment | DSCR loan |
| Assets are large and the return is documented and regular | Price asset based against conventional, which may still be cheaper |
That last row deserves emphasis. If your dividends and distributions are consistent and documented over two years, a conventional lender may count them directly, and conventional financing usually costs less. Asset based is the answer when the conventional calculation fails, not a default upgrade.
Virginia has an unusually large population of people who fit this profile and do not know the product exists: career federal employees and military retirees with substantial Thrift Savings Plan balances and pensions, government contractors who sold a stake, and a steady stream of retirees moving into the Shenandoah Valley, Williamsburg and the Northern Neck from higher-cost markets with the proceeds of a sold house.
That last group has a specific problem worth naming. Selling in one market and buying in another often means the purchase happens before the sale completes, so the assets exist but the income does not, and the timing is exactly wrong for a conventional file. Asset based financing handles it. So does a bridge arrangement in some cases, and which one fits depends on the sequence.
On loan size, the 2026 conforming limit is $832,750 across most of Virginia and $1,249,125 in the high-cost Washington metro counties, per the Federal Housing Finance Agency. Asset based files frequently land above those limits, and jumbo asset based programs apply heavier reserve requirements on top of the down payment, so plan for both. There is more on how that split works across the state on the Virginia mortgage broker page.
I will run the calculation across the range of lender approaches and tell you what the spread looks like for your particular mix. No credit pull required for that.
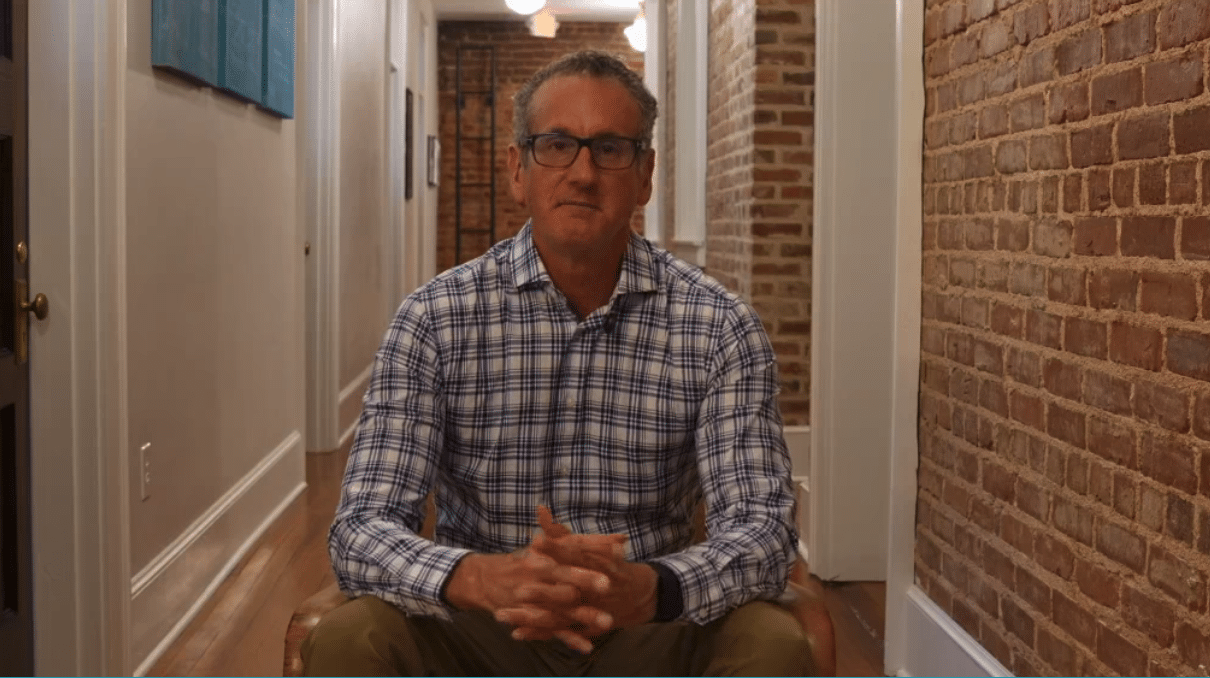
I am Scott Hastings, a mortgage broker with Arbor Financial Group. A good share of my work is borrowers who could pay cash but would rather not, and who keep being declined by lenders reading only the bottom line of a tax return.
Licensed in 13 states including Virginia. Individual NMLS ID 926762, verifiable on NMLS Consumer Access.
Mortgages by Scott has been accredited by the Better Business Bureau since 2015, and I have been originating mortgages for more than twenty years. WalletHub named me one of the best mortgage brokers in Charlotte for 2026.
No. Nothing is liquidated, sold or pledged. The lender counts your eligible assets and divides them by a set number of months to produce a qualifying income figure, and that calculation is purely a measurement of capacity. Your accounts stay invested and you are under no obligation to draw on them. The money you use for the down payment and closing costs does come out of the calculation first, since the same funds cannot both buy the property and qualify you for it.
They total the eligible assets, reduce the non-cash holdings to account for volatility, then divide by a fixed number of months, commonly 60, 84 or 120 depending on the lender. That divisor is the single biggest variable in the whole product. The same assets divided by 60 months produce double the qualifying income they produce divided by 120, and both approaches are entirely ordinary, which is why it is worth comparing lenders rather than accepting the first calculation you are shown.
Usually yes, with a reduction, and how steep that reduction is depends largely on your age. Once you are past the age at which you can withdraw without penalty, retirement accounts tend to be treated much like a brokerage account. Below that age, treatment varies considerably between lenders, from a heavier reduction to excluding the accounts entirely. If a significant share of your wealth sits in retirement accounts and you are not yet at that age, this is the detail that decides which lenders are worth approaching.
Not quite, though they overlap. An asset based mortgage builds a qualifying income figure from documented assets, so there is verification, just of a different thing. You will supply statements, and those assets generally need to have been in place for a documented period rather than appearing recently. What you are not supplying is tax returns, pay stubs or employment verification as the basis for qualifying.
This is one of the more common reasons people end up here. The assets exist but the sale has not completed, so a conventional lender sees neither sufficient income nor the proceeds. Asset based financing can work on the strength of what you already hold, and in some situations a bridge arrangement fits better. Which one is right depends on the sequence and timing of the two transactions, so it is worth mapping out before you make an offer.
Both still matter, even though income does not enter the file in the usual way. Credit requirements are generally similar to other non-QM programs and your score still prices the loan. Down payment expectations are typically higher than a conventional purchase, and jumbo asset based files, which these often are in Northern Virginia, carry heavier reserve requirements on top of the down payment. Plan for money remaining after closing rather than just money at closing.
Send me rough balances by account type and I will run the calculation across the range of lender approaches, with no credit pull.
Text Scott: 704-890-7168 Call 704-890-7168Scott Hastings, individual NMLS #926762. Arbor Financial Group, 121 N Main St Ste 202, Mooresville, NC 28115. Phone and text 704-890-7168. Licensed to originate mortgage loans in Virginia.
Equal Housing Opportunity. This page is general information about loan programs and is not a commitment to lend, a loan approval, or an offer of credit. Program availability, qualifying guidelines, credit score minimums, down payment and reserve requirements vary by lender and are subject to change. Nothing here is legal, tax or financial advice.
Loan limit figures are published by the Federal Housing Finance Agency and are current for 2026. Asset eligibility, reduction percentages and the divisor used vary by lender and are subject to change. Consult your own tax and financial advisers before making decisions about retirement or investment accounts.