North Carolina · NMLS #926762
Qualify on the gross income your 1099s report, not on the Schedule C that survives your deductions. Built for contractors, travel nurses, owner-operators and commissioned agents.
The short version. A 1099 program qualifies you on the gross income reported on your 1099 forms, minus a fixed expense factor that is usually far smaller than the deductions on your tax return. No Schedule C. Strongest when nearly all of your income arrives on a form. Call or text me at 704-890-7168.
A 1099 program qualifies you on the gross income reported on your 1099 forms, reduced by a fixed expense factor, with no Schedule C in the file at all.
That single sentence is the entire product, and it matters because the Schedule C is where contractors lose. You bill $190,000. You deduct mileage, a home office, equipment, continuing education, health insurance, a phone, half your self-employment tax, and you land at $104,000 of net profit, every dollar of it legitimate. A conventional underwriter is required to use the $104,000. A 1099 lender starts at the $190,000 and applies its own factor, often somewhere in the 10 to 25 percent range, which lands you nearer $150,000.
Same person. Same year. A qualifying income roughly forty percent higher, because the two lenders are reading different documents.
These two products get pitched interchangeably. They are not interchangeable.
| 1099 program | Bank statement program | |
|---|---|---|
| What it reads | Your 1099 forms | Deposits into your account |
| Expense factor | Often 10 to 25 percent | Often 20 to 50 percent |
| Paperwork | One or two forms per payer | 12 or 24 months of statements |
| Best for | Contractors paid by a handful of payers | Businesses with many customers |
| Breaks down when | Much of your income is not on a 1099 | Personal and business money are mixed |
The rule of thumb is simple. If substantially all of your income arrives on 1099s, the 1099 program almost always qualifies you for more, because the expense factor is lower and the paperwork is a fraction of the work. If you invoice forty different customers and half of them pay you without issuing a form, the bank statement route is the honest one.
Run both. It takes an afternoon and the spread is frequently large.
This is not a niche product in this state. Consider who gets paid on a 1099 here:
If you recognized yourself in that list, the program was built for your paperwork.
Two years of 1099s is the default. Plenty of lenders will work from one.
One year helps when last year was materially better than the year before. It hurts when the reverse is true, and it costs a little in pricing because the lender has half the evidence. The thing people get wrong is treating this as a paperwork preference rather than a math question, when the two periods regularly produce qualifying incomes thousands of dollars apart and the only way to know which direction is to add them up.
Add them up first. Then choose.
A contract software engineer in Raleigh, billing through two staffing agencies, buying at $540,000 with 10 percent down.
His 2025 Schedule C showed $118,000 of net profit after a home office, two machines, a travel line and health insurance premiums. The conventional calculation, using a two year average of net profit, put him near $9,400 a month. The 1099 program put him at $15,654. On a 45 percent debt ratio that is the difference between roughly $420,000 of house and the $540,000 one he actually bought.
Contract work has gaps. A thirteen week assignment ends, you take three weeks, the next one starts. An agency contract lapses while a renewal sits in legal. None of that is unusual and all of it looks alarming to an underwriter reading a bare income history.
Three things help, and none of them are complicated. A letter of explanation that treats the gap as ordinary rather than apologizing for it. A signed contract or a letter from the agency showing current work and its term. Continuity of payer, because two years with the same two agencies reads as stability in a way that eight different payers does not, even at identical income.
What does not help is hoping nobody notices. They notice.
The underwriter is answering one question: will this income continue? Everything you send either supports that or undercuts it.
Rarely the income. The declines I see cluster into four shapes, and all four are avoidable if you know about them before you apply.
None of those are income problems. They are file problems, and file problems get solved in advance or they get solved badly.
You cannot walk into a branch and ask for a 1099 program. The lenders who offer these do not take retail applications, they sell through brokers, and the handful of retail banks that have built something similar in-house tend to price it conservatively because they have no competition in the room.
What that means in practice is that the spread between lenders on an identical file is wider here than anywhere else in residential lending. One lender uses a 25 percent expense factor for your occupation. Another uses 10. One wants two years, another is comfortable with one. One will exclude a business credit card with twelve months of payment history from the business account, another will not consider it. None of that is visible from the outside, and none of it is published.
That is the argument for a broker, and it is the only argument I will make for myself on this page. I am not cheaper because I am nicer. I am useful because I can send the same file to several of these lenders in a week and show you what came back.
If your income arrives on 1099s, this is usually the strongest non-QM option available to you. A bank statement loan applies a heavier expense factor. An asset based program ignores income entirely and is a better fit for people with large balances and small reported earnings. A DSCR loan only exists for investment property. And conventional financing remains the cheapest money in the market whenever your returns can actually support the file, which is worth checking honestly before you pay non-QM pricing.
I will run the conventional math first. If it works, I will tell you to take it.
Your closing will run through an attorney. North Carolina requires a licensed North Carolina attorney to handle the title opinion and the deed, under G.S. 84-2.1 and State Bar Advisory Opinion 2002-1, and the choice of attorney is yours. On a non-QM file, pick one who has closed these before, because unfamiliar closing instructions produce questions at nine in the morning on closing day.
The 2026 conforming limit is $832,750 for a one unit property in every county in the state, with no high-cost designation anywhere. With Charlotte’s August 2026 median at $429,995 and Raleigh’s at $420,000, most contractor files are nowhere near that ceiling, which means the obstacle is almost never loan size. It is the Schedule C.
I will come back with a qualifying income under the 1099 program, the same figure under a bank statement program, and the conventional number for comparison. No credit pull to get there.
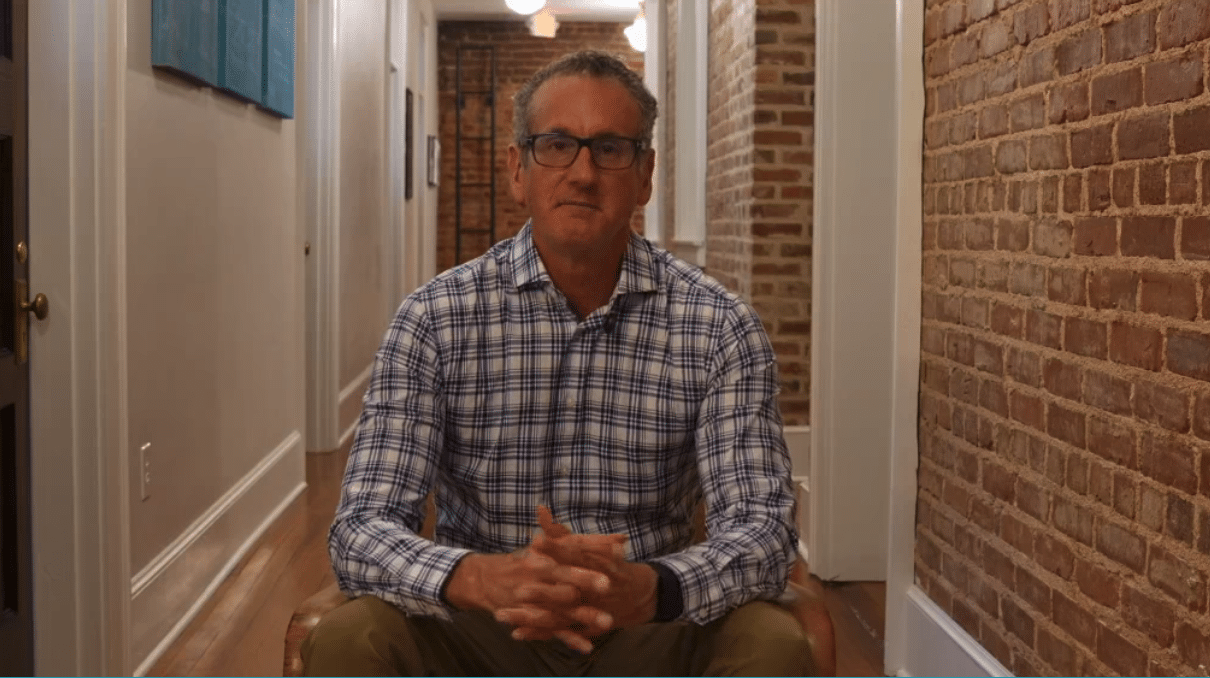
I am Scott Hastings, a mortgage broker with Arbor Financial Group, working from 121 N Main St in Mooresville. North Carolina is home, and contract earners are a large share of my files: travel nurses, RTP and Charlotte technology contractors, owner-operators and commissioned agents.
Licensed in 13 states including North Carolina. Individual NMLS ID 926762, verifiable on NMLS Consumer Access.
Mortgages by Scott has been accredited by the Better Business Bureau since 2015, and I have been originating mortgages for more than twenty years. WalletHub named me one of the best mortgage brokers in Charlotte for 2026.
Yes. A 1099 program qualifies you on the gross income shown on your 1099 forms, reduced by a fixed expense factor, with no Schedule C in the file. It usually produces a materially higher qualifying income than a conventional loan for the same borrower.
Two years is the common requirement and many lenders will work from one. One year helps when the most recent year is your stronger year and hurts when it is not, so compare both before choosing. Shorter histories often carry slightly higher pricing.
It depends on where your income lands. If nearly all of it arrives on 1099s, the 1099 program usually wins because the expense factor is lower. If a lot of your revenue is paid without a form being issued, bank statements are the honest route.
No, but they need explaining. A letter describing the gap as normal for your field, a current contract showing active work, and continuity with the same payers over two years all help an underwriter conclude the income will continue.
Gross, reduced by the lender’s expense factor rather than by your actual deductions. That is the whole point of the program. Factors commonly fall in the 10 to 25 percent range and vary by lender and by occupation.
Yes. North Carolina requires a licensed attorney to handle the title opinion and the deed under G.S. 84-2.1 and State Bar Advisory Opinion 2002-1. You select the attorney, and on a non-QM loan it is worth selecting one who has closed this type of file before.
Send me your last two years of 1099s. I will price the 1099 program, the bank statement program and conventional side by side so you can see the spread, with no credit pull.
Text Scott: 704-890-7168 Call 704-890-7168Scott Hastings, individual NMLS #926762. Arbor Financial Group, 121 N Main St Ste 202, Mooresville, NC 28115. Phone and text 704-890-7168. Licensed to originate mortgage loans in North Carolina.
Equal Housing Opportunity. This page is general information about loan programs and is not a commitment to lend, a loan approval, or an offer of credit. Program availability, qualifying guidelines, credit score minimums, down payment and reserve requirements vary by lender and are subject to change. Nothing here is legal, tax or financial advice.
1099 income loan programs are non-QM products. Expense factors, documentation requirements and the number of years required vary by lender and are subject to change. Figures used in examples on this page are illustrative and are not quotes, offers or predictions of what any particular borrower will qualify for.