For business owners who found the next house and don’t want to lose it waiting on the old one to sell.
Yes, you can buy a house before selling yours. The hard part usually isn’t the down payment. It’s that the lender has to qualify you carrying both mortgages, unless your current home is already under contract and the buyer’s financing contingency has cleared.
If you’re self-employed and your tax returns show a lot less income than your business actually makes, that two-payment test is where most of these deals die. The ways around it are a HELOC opened before you list, Fannie Mae’s new rent offset rule if you keep the old house, or a bank statement loan that qualifies you on deposits instead of tax returns.
So you found the house. Maybe it’s the lot on the water you’ve been watching for two years, maybe it’s the right school district at the right time. And now you’re running the math in your head. If I list mine first, I could lose this one. If I buy this one first, can I even get approved with two payments?
That’s a fair worry, and it’s exactly where most people get stuck. The good news is that it’s usually a sequencing problem, not a dead end. If you want to buy a house before selling yours, the order you do things in matters more than almost anything else.
When you apply for the new loan, the lender counts your current house payment as a debt. That’s principal, interest, taxes, insurance and any HOA dues, which lenders call PITIA. Put the new payment on top of it and your debt-to-income ratio jumps. In other words, the lender is asking one question: could you carry both houses if the old one never sold?
There’s one clean exception. Under Fannie Mae guideline B3-6-06, the lender can leave your current payment out if you have an executed sales contract on your current home and the buyer’s financing contingency has been cleared. So if your house is under contract and your buyer’s loan is solid, you may only be qualifying on one payment.
Here’s where business owners get hit twice. A W-2 earner making $250,000 shows $250,000. You might run far more than that through your business and show half of it on your tax return after write-offs, depreciation and the salary your CPA set for your S corp. Now the lender is asking whether that smaller number can carry two mortgages, and on paper it usually can’t, right? Not because you can’t afford it. Because your tax return says you can’t. If that sounds familiar, here’s how write-offs affect your approval.
For most people, the next down payment is sitting in the current house as equity. You can’t spend equity until you sell or borrow against it. These are the realistic ways to borrow against it.
A home equity line of credit lets you draw against your current home for the down payment, then pay it off when the house sells. Fannie Mae allows borrowed funds secured by another asset you own to be used for a down payment, and the HELOC payment gets counted in your debt ratio on the new loan.
The catch most people learn too late: most HELOC lenders won’t open a line on a home that’s already listed for sale. So open the HELOC first and list second. Get that backwards and this option is gone. I walk through the equity side in more detail in how to use your home equity to buy another property.
A bridge loan is a short-term loan against your current home, usually meant to last months, not years, and paid off when the house sells. It costs more than a HELOC and fewer lenders offer it. Where it earns its keep is when the house is already listed, or the HELOC limit isn’t big enough for the down payment you need. The payment or structure still has to fit your qualifying on the new loan.
People ask about this one, so I’ll be straight. A cash-out refinance on the current home replaces your first mortgage, so you pay full closing costs on a loan you plan to pay off in a few months. And if your current rate is lower than what’s available today, you give that up for nothing. There are cases where it fits, but it’s rarely the first tool I reach for here.
If you’d rather keep the old house as a rental, the rules just changed. On September 2 2026 Fannie Mae gave the departing residence, the home you’re moving out of, its own section of the Selling Guide, B3-3.8-05. Lenders could start using it right away and must use it for applications dated November 1, 2026 or later.
Here’s how it works. The lender can no longer use a lease. Instead it establishes market rent from an appraisal, a rent schedule, or a market analysis with at least three comparable rentals. It takes 75 percent of that rent, then subtracts the old home’s full payment. If the result is positive, it cancels out the old payment. If it’s negative, the shortfall counts as debt.
In other words, you don’t need a tenant lined up to get credit for the rent, but the rent can only cancel out the old payment. It can’t add to your income. And if you have less than 12 months of documented landlord experience, the lender has to see six months of the old home’s payment in reserves, on top of any other reserves the loan requires. That reserve number is what trips people up.
Freddie Mac handles this differently, and FHA is stricter still. On FHA, rent from the home you’re leaving generally only counts if you’re relocating more than 100 miles away and have at least 25 percent equity. Before you go this route, read renting out a house with a mortgage to buy the next one and how long you need to live in a home before renting it out.
If the two-payment math fails on your tax returns, that’s when I look at a bank statement loan. It qualifies you on 12 or 24 months of business or personal bank deposits instead of your tax returns. You still have to pass the same two-payment test. You just pass it against the income your business actually produces. You can get a rough read on that number with the self-employed income calculator.
If you decide to keep the old house as a rental, a DSCR loan lets you finance or refinance it based on the rent it brings in rather than your personal income.
The honest tradeoff: non-QM loans cost more than conventional loans, in rate and in fees. Whether that’s worth it depends on how much the new house matters and how long you’ll hold the loan. Some borrowers refinance later once their tax returns catch up, but nobody should count on rates cooperating. Run the numbers both ways before you commit.
This is a made-up example to show the math, not a real client. Numbers are rounded, and the payments are assumptions, not quotes.
Say a business owner wants to buy before selling. The current house payment is $2,600 a month. The new house will run $5,400. A HELOC on the current home covers the down payment at $1,100 a month, and a car and credit cards add $900.
| Monthly debt | Amount |
|---|---|
| Current home payment | $2,600 |
| New home payment | $5,400 |
| HELOC payment | $1,100 |
| Car and credit cards | $900 |
| Total | $10,000 |
On tax returns, this owner shows $13,000 a month after write-offs. That’s a 77 percent debt ratio, and that’s a no almost anywhere. On a bank statement loan, the same business shows $25,000 a month in qualifying income after the lender’s expense factor. Now the ratio is 40 percent, and that’s a file worth sending to underwriting.
If the current house goes under contract before closing and the buyer’s financing contingency clears, many lenders will drop that $2,600 out of the math entirely. Then the old house sells, the HELOC gets paid off, and the owner is back to one house and one payment.
When the old house closes, you’ll have cash. Pay off the HELOC first. If there’s money left over and you want a lower payment, ask about a recast. In other words, you make a large principal payment and the servicer re-amortizes the loan over the remaining term at the same rate, so the payment drops without a refinance.
Many conventional loans allow it, usually for a fee. FHA and VA loans generally don’t, and non-QM servicers vary. Ask before you pick the loan, not after.
The old house takes longer to sell than you planned. Run your budget as if it takes six months, not six weeks. If it stalls, here’s how to think about renting it instead.
The reserves come up short. Between the down payment, closing costs and the reserves the lender wants, cash gets tight fast, especially if you’re keeping the old house.
You list before you open the HELOC. That’s the most common unforced error in this whole process.
You sign a lease to help you qualify. On a Fannie Mae loan, a lease on your departing residence no longer counts for this. Talk to your lender before you sign anything.
An appraisal comes in low. On either house. A low number on the old home shrinks your HELOC, and a low number on the new one raises the cash you need.
Want to see your own payment on the new house first? Try the self-employed mortgage payment calculator.
Yes, as long as you can qualify carrying both payments, or your current home is under contract with the buyer’s financing contingency cleared. If your tax returns show a lot less income than your business really makes, a bank statement loan often qualifies you more easily because it uses your deposits instead of your tax returns.
Usually, yes. Fannie Mae lets the lender leave your current payment out only if you have an executed sales contract on your current home and the buyer’s financing contingency has been cleared. If you’re keeping the old house as a rental, market rent can offset some or all of its payment.
Most HELOC lenders won’t open a line on a home that’s currently listed for sale. If you plan to use your equity for the next down payment, open the HELOC first and list the house after.
Not on a Fannie Mae loan under its September 2026 update. The lender uses market rent from an appraisal, a rent schedule, or a market analysis with at least three comparable rentals, and a lease can’t be used for a departing residence. Lenders must follow it for applications dated November 1, 2026 or later. Freddie Mac and FHA have different rules.
Usually a HELOC costs less, if you can open it before you list and the line is big enough. A bridge loan fills the gap when the house is already listed or the HELOC limit is too low. Either way, the payment still has to fit your qualifying on the new loan.
You carry both payments until it does, so plan for that before you buy. Your options at that point are a price cut, renting it out, or financing it on its rent with a DSCR loan if it makes sense to keep as an investment.
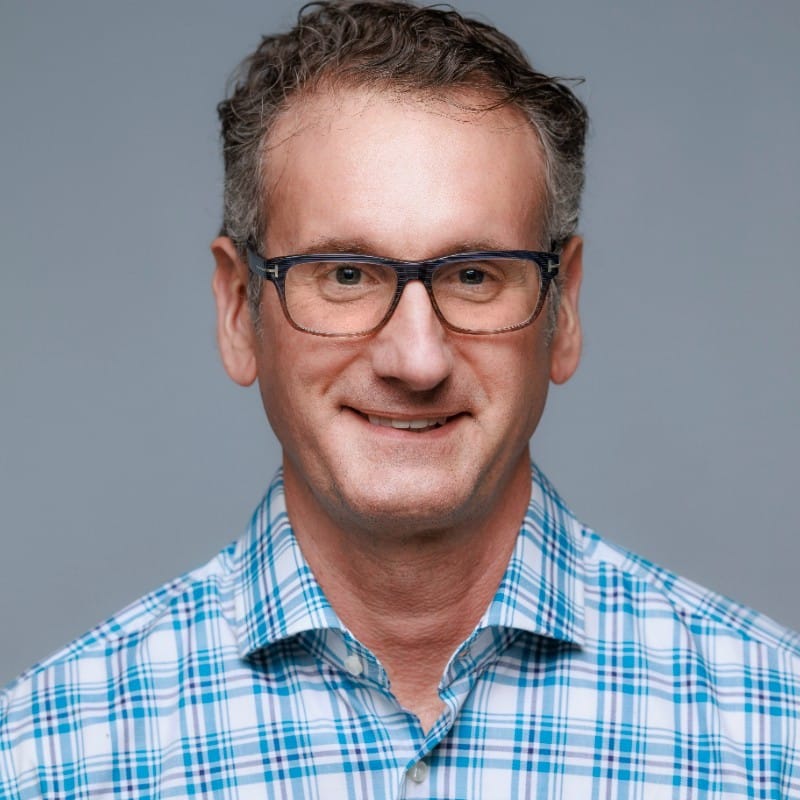
I’m Scott Hastings, a mortgage broker with Arbor Financial Group, based in Mooresville. Most of the people I work with are business owners and real estate investors whose tax returns don’t tell the whole story.
Because I’m a broker, I can take the same file to conventional and non-QM lenders. So if the two-payment math doesn’t work on one program, we look at the next one instead of stopping at no.
Text me the price of the new home, roughly what you owe on your current one, and whether you plan to sell or keep it. I’ll tell you which of these paths fits and what a lender will want to see.
Scott Hastings, NMLS #926762. Mortgages by Scott, Arbor Financial Group. 121 N Main St Ste 202, Mooresville, NC 28115. Equal Housing Opportunity.
This page is general information, not a commitment to lend. Loan programs, guidelines, terms and eligibility vary by lender and are subject to underwriting approval. Rules cited are current as of October 2026 and can change. This is not tax or legal advice.