For business owners whose CPA set a small salary on purpose, and now a lender wants to know what you really make.
And no, you can’t just hand over your W-2 the way you did when you worked for someone else. If you own 25 percent or more of the company, the lender needs your business returns too. The good news is that your salary isn’t the ceiling. On a full-documentation loan, the lender counts the W-2 your S corp pays you, plus your share of the company’s profit from your K-1, and adds back non-cash expenses like depreciation.
The catch is that the lender has to see one of two things: that you actually took that profit out as distributions, or that the business has enough cash on hand that you could. If write-offs pushed your K-1 too low to work, a bank statement loan using your business deposits is usually the next place to look.
So your CPA did their job. They set a reasonable salary, kept your payroll taxes down, and let the rest of the profit flow through the S corp. That’s smart tax planning, and the IRS expects a reasonable salary for owners who work in the business anyway.
Then you talk to a lender, and the first number anyone looks at is your W-2. It’s a fraction of what the business actually makes. Here’s the thing, though. Most S corp owners qualify for more than they expect, as long as the lender reads the returns the right way. An S corp owner mortgage is really a cash flow question, not a salary question.
Not if you own 25 percent or more of the company that pays you. I get this call a lot, and it makes sense. You get a W-2 and pay stubs just like you did at your old job, so why would the mortgage be any different? Because the lender treats you as self-employed once you own a quarter or more of the business. Your W-2 is still part of your income. It just isn’t the whole file anymore.
In other words, the lender is going to ask for your business returns too, because the company paying you is you. A W-2 from your own company can’t show a stable job the way an outside employer’s can, since you’re the one deciding what goes on it.
If you recently left a job to start or buy the company, there’s a second issue: time. Fannie Mae generally wants a two-year history of self-employment income. With less than two years, the lender can still consider it if your most recent signed personal and business returns show a full 12 months from the current business, and your earlier work was in the same field at the same or higher income. Your old employer’s W-2s help show that history, but they can’t stand in for the new company’s income. More on that in getting a mortgage without a two-year work history.
Here’s where this goes wrong. A lender takes the W-2 at face value at pre-approval, then underwriting finds the ownership later, in your tax transcripts or the K-1 on your personal return. Now the file gets re-underwritten weeks into the deal, sometimes with a contract deadline coming. Tell your lender you own the company on day one.
And here’s the upside people miss. Being treated as self-employed is usually good news for an S corp owner on a low salary, because it’s what lets the lender count your K-1 income and add-backs on top of the W-2. If you own less than 25 percent, the lender generally treats you like an employee and your W-2 does most of the work.
If you own 25 percent or more of a business, Fannie Mae treats you as self-employed. That means the lender doesn’t stop at your W-2. It builds a cash flow analysis from your personal return and your business return, the Form 1120S.
There are three pieces. First, the W-2 wages the corporation paid you. Second, your share of the ordinary business income on your K-1. Third, add-backs from the 1120S: depreciation, depletion and amortization, which reduced your profit on paper without taking any cash out of the business.
Then the lender subtracts a few things, like notes and mortgages the business owes that come due within a year, and meals and travel that weren’t deductible. In other words, the lender is trying to rebuild the cash the business produced for you, not the number you paid tax on.
If your CPA took a big depreciation deduction on equipment or a vehicle, that’s usually good news here. I go deeper on that in how depreciation helps self-employed borrowers qualify.
This is the part most people have never heard of, and it’s where S corp files fall apart. Under Fannie Mae guideline B3-3.6-07, K-1 income can only go into your qualifying income if one of two things is true.
You have a stable history of taking distributions. If your K-1 shows you’ve consistently pulled cash out of the business at a level that matches the income being used, the lender doesn’t need anything more.
Or the business has the cash to support it. If you haven’t taken distributions, the lender has to confirm the business has enough liquidity that you could. That’s usually measured from the balance sheet on your business return, using a standard ratio of current assets to current liabilities. Businesses that carry a lot of inventory get tested on a stricter version that leaves inventory out.
So here’s how a strong year turns into a weak file. Your K-1 shows good profit, but you left that money in the business to buy equipment or hire, and the balance sheet shows thin cash. Now the lender may not be able to count the K-1 at all, and you’re back to qualifying on your salary. Nothing about your business changed. The paper just didn’t support it.
This is a made-up example to show the math, not a real client. It assumes both years of returns look about the same.
Say you own 100 percent of an S corp. Your CPA pays you a $60,000 salary. The 1120S shows $95,000 of ordinary business income flowing to your K-1, after $35,000 of depreciation on equipment. You’ve taken steady distributions every year.
| Income piece | Annual |
|---|---|
| W-2 salary from your S corp | $60,000 |
| K-1 ordinary business income | $95,000 |
| Depreciation added back | $35,000 |
| Qualifying income | $190,000 |
That’s about $15,800 a month. If a lender only looked at your W-2, you’d be qualifying on $5,000 a month. Same business, same bank account, more than three times the income on paper.
Two things can change that number. Lenders usually average two years, so if last year was lower, the average comes down. And if income dropped from one year to the next, the lender may use the lower year or need an explanation for the decline.
Real expenses stay subtracted, even the ones that feel personal. The payments, fuel and insurance on a truck you run through the business, your phone, the deductible part of your meals: if they were real money out the door on the return, the lender treats them as real. Only the depreciation piece of that truck comes back.
This is where a lot of business owners get surprised. Every write-off saved you tax, and every write-off that isn’t a non-cash expense also lowered your qualifying income. If that’s your situation, read how write-offs affect your mortgage approval.
Sometimes the returns can’t carry it. The write-offs were heavy, the business just had its best year and the returns haven’t caught up, or the distributions don’t line up with the K-1 and the balance sheet is thin.
That’s when I look at a bank statement loan. For an S corp owner, business bank statements usually work better than personal ones, because your personal account only shows your salary and the distributions you took. The lender takes 12 or 24 months of business deposits and applies an expense factor, a set percentage or one backed by your CPA, to estimate income. In other words, you qualify on what comes into the business, not what’s left after your CPA’s planning.
The tradeoff is cost. Bank statement loans price higher than conventional loans, in rate and in fees. Some owners refinance later once the tax returns support it, but don’t build your plan around rates cooperating. There are other routes too, which I cover in getting a mortgage without tax returns.
How you pay yourself is your CPA’s call, not mine, and I’d never tell you to pay more tax just to get a loan. But if you’re planning to buy in the next year, get your lender and your CPA talking before the next return gets filed.
A few things are worth that conversation. The split between salary and K-1 matters less than people think, because the lender counts both. What matters more is whether your distributions line up with the K-1 income and whether the balance sheet shows cash. And on Fannie Mae loans, if the automated approval allows it and you’ve owned at least 25 percent of the business for five years, one year of returns may be enough instead of two.
Want a rough read on your number first? Try the self-employed income calculator, or see the full picture in the self-employed mortgage qualification guide.
Not if you own 25 percent or more of the company that pays you. Fannie Mae treats you as self-employed, so the lender needs your personal and business returns, not just your W-2. If you started the business less than two years ago, you’ll also need at least one full year of returns from the new company and prior work in the same field. The upside is that the lender can count your share of the K-1 income and add back depreciation on top of your salary.
Then the lender has to confirm the business has adequate liquidity to support withdrawing that income, usually by comparing current assets to current liabilities on the balance sheet of your business return. If the business is thin on cash, the lender may not be able to count the K-1 income.
Usually not on a full-doc loan. Depreciation, depletion and amortization on the business return are non-cash expenses, so the lender adds them back to your income. Real expenses like vehicle payments, fuel and phone bills stay subtracted.
Usually two years of personal and business returns. On a Fannie Mae loan, one year may be enough if the automated approval allows it and you’ve owned at least 25 percent of the business for the past five years.
Talk to your CPA before changing anything for a mortgage. For the lender, the split between salary and K-1 income matters less than people think because both can count. Consistent distributions and a healthy balance sheet usually matter more.
When write-offs push your K-1 income too low, when income just jumped and the returns haven’t caught up, or when distributions and business cash don’t support the K-1. A bank statement loan qualifies you on 12 or 24 months of business deposits instead, at a higher cost than a conventional loan.
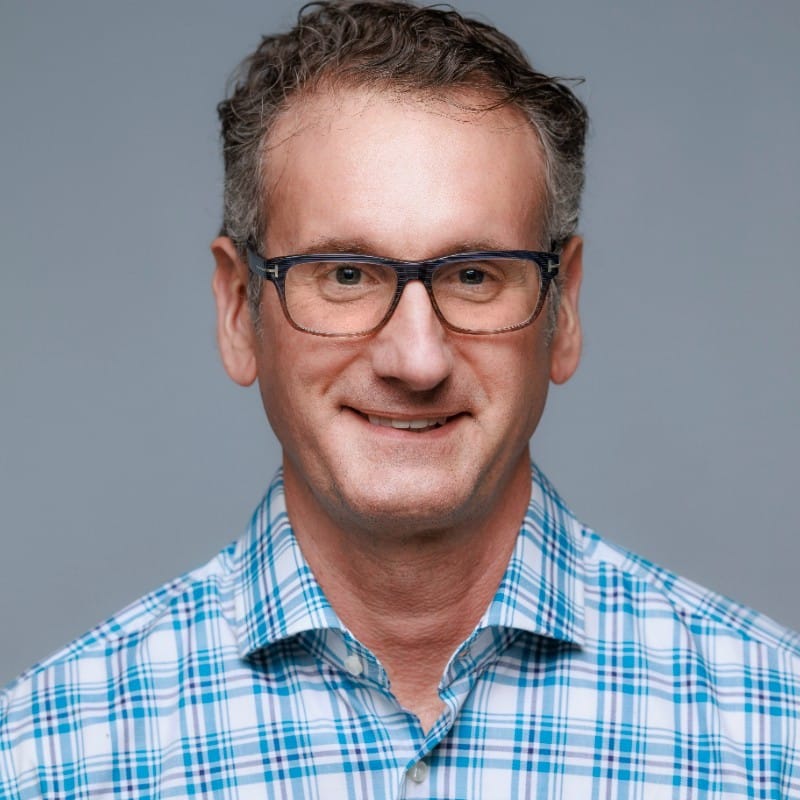
I’m Scott Hastings, a mortgage broker with Arbor Financial Group, based in Mooresville. Most of the people I work with are business owners and real estate investors whose tax returns don’t tell the whole story.
Because I’m a broker, I can take the same file to conventional and non-QM lenders. So if your returns don’t carry it on one program, we look at the next one instead of stopping at no.
Text me your W-2 salary from the S corp, the ordinary income on your K-1, and what you’re hoping to buy. I’ll tell you how a lender is likely to read it and which loan fits.
Scott Hastings, NMLS #926762. Mortgages by Scott, Arbor Financial Group. 121 N Main St Ste 202, Mooresville, NC 28115. Equal Housing Opportunity.
This page is general information, not a commitment to lend. Loan programs, guidelines, terms and eligibility vary by lender and are subject to underwriting approval. Rules cited are current as of October 2026 and can change. This is not tax or legal advice.